How should the value of an artificial intelligence company be measured?
The answer may depend on the sophistication of its models, the number of people using its technology, or the revenue it generates.
But when an AI company prepares to enter the public stock market, another question becomes unavoidable.
How much will it cost to develop and operate AI in the years ahead?
The technical performance of an AI model and the economic value of the company producing it do not necessarily move in the same direction.
New financial disclosures now offer a closer look at this challenge.
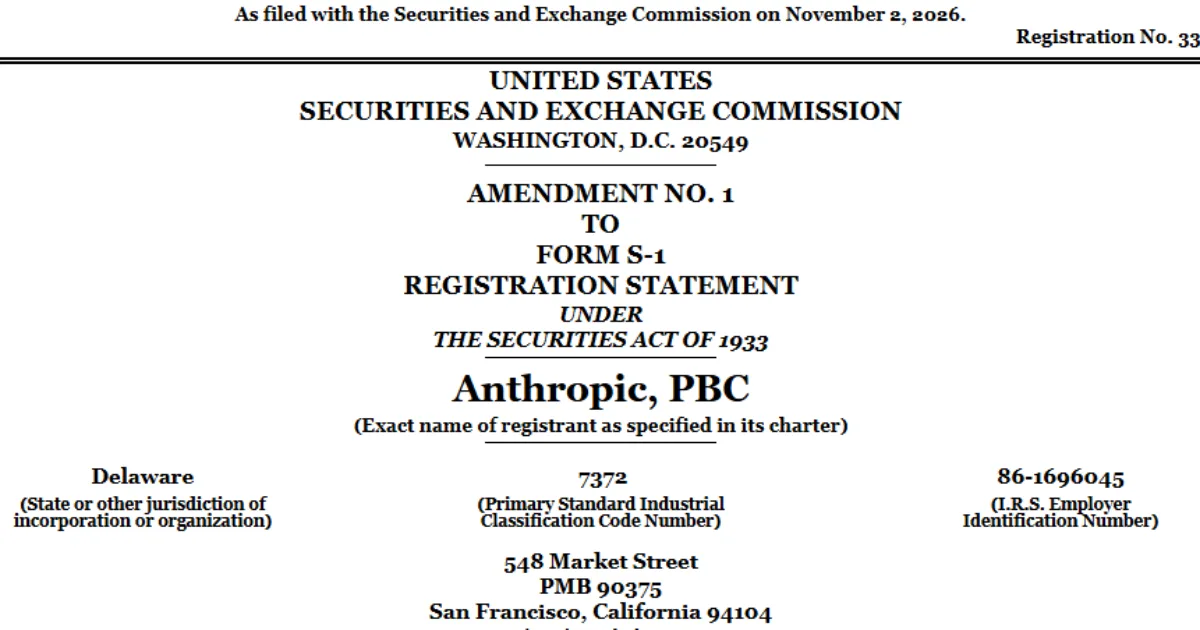
Anthropic, the developer of the Claude AI chatbot, has filed an amended registration statement for its proposed initial public offering with the U.S. Securities and Exchange Commission.
After publicly filing its initial registration statement on October 26, 2026, Anthropic submitted an amendment on November 2 using Form S-1/A.
The company plans to list on the Nasdaq Global Select Market under the proposed ticker symbol ANT.
The filing reveals both the extraordinary growth potential of the AI industry and the enormous costs required to sustain that growth.
Anthropic generated approximately $17 billion in revenue during the third quarter of 2026.
That is remarkable considering that its revenue for the entire previous year was approximately $4.6 billion.
Yet the company reported a net loss of approximately $23.3 billion during the same quarter.
An even larger figure appears elsewhere in the filing.
Anthropic disclosed approximately $895.4 billion in aggregate purchase and lease commitments associated with computing infrastructure and data centers.
Of that total, approximately $447.5 billion is expected to be spent by the end of 2030.
A company that began as an AI model developer is now managing future infrastructure commitments measured in hundreds of billions of dollars.
This is not simply a story about Anthropic's balance sheet.
It illustrates how competition in artificial intelligence is moving beyond software toward data centers, semiconductors, electricity, and capital financing.
The central question raised by Anthropic's IPO filing is not how quickly the company is growing. It is whether Anthropic can sustainably finance the enormous computing infrastructure required to maintain that growth.
1. Quarterly Revenue Has Grown to Nearly Four Times the Previous Year's Total
Anthropic's revenue growth has been extraordinary even by the standards of high-growth software companies.
In 2023, the company generated $41 million in revenue.
That increased to $386 million in 2024.
By 2025, annual revenue had reached $4.585 billion.
Growth accelerated even further in 2026.
During the first nine months of the year, Anthropic generated $33.242 billion in revenue.
That represented an increase of 1,206% from the $2.545 billion recorded during the same period in 2025.
Third-quarter revenue alone reached approximately $16.956 billion.
That was about 3.7 times the company's revenue for all of 2025.
Such growth suggests that AI models are rapidly moving beyond experimental applications and becoming services used in actual enterprise operations.
Anthropic identified coding, complex reasoning, AI agents, and computer-use capabilities as important drivers of corporate demand.
But exceptionally high growth rates cannot be assumed to continue indefinitely.
Revenue grew approximately 47% between the second and third quarters of 2026.
That remained an extraordinary quarterly increase, but it was slower than the approximately 144% sequential growth recorded in the second quarter.
Anthropic explicitly warned in its registration statement that it does not expect its current elevated revenue growth rates to continue.
As its business expands, the extraordinary growth associated with early market adoption and rapid customer acquisition may naturally moderate.
The filing therefore reveals two developments simultaneously: explosive business expansion and the possibility of a gradual slowdown in growth rates.
2. How Does Claude Generate Revenue?
Anthropic's growth is not driven solely by consumer subscriptions to Claude.
Its registration statement identifies usage-based billing as a major revenue model.
The company describes its approach as "pay-for-intelligence."
Customers pay according to the AI models they use and the volume of tokens processed.
In simple terms, businesses pay for the AI computing services they consume.
Using more powerful models to complete complex tasks can increase costs.
For simpler activities, customers can choose less expensive models.
Anthropic said it serves these different needs through model families including Mythos and Fable, Opus, Sonnet, and Haiku, which offer different performance and cost characteristics.
During the first nine months of 2026, usage-based revenue totaled approximately $26.3 billion.
That represented roughly 79% of total revenue.
Subscription revenue amounted to approximately $6.9 billion, accounting for about 21%.
These figures indicate that Anthropic is not primarily a conventional chatbot subscription business.
A substantial portion of its revenue depends on how intensively businesses and developers use its AI models.
This creates an important economic distinction.
For many conventional subscription software companies, the incremental cost of serving customers can remain relatively limited even as users access the software more frequently.
Generative AI operates differently.
Every model request requires computation.
When usage increases, revenue can grow, but the computing resources required to provide the service also increase.
For AI companies, cost per token and computing efficiency can therefore be as important as revenue growth.
3. More Than 11,900 Customers Generate at Least $100,000 in Annualized Revenue
Anthropic's expanding enterprise business is also evident in its customer figures.
At the end of 2023, approximately 20 customers generated at least $100,000 in revenue on a trailing-twelve-month basis.
That number increased to approximately 200 by the end of 2024.
It reached approximately 1,500 by the end of 2025.
By September 2026, more than 11,900 customers met that threshold.
More than 1,900 customers generated at least $1 million in annualized revenue.
Approximately 250 customers generated at least $10 million.
These figures indicate that Claude has moved beyond limited experimentation within technology companies and is attracting substantial enterprise spending.
According to Anthropic, more than half of Fortune 500 companies were among its customers generating at least $100,000 over the preceding twelve months.
More than 30% of companies in the Global 2000 also met that threshold.
This customer base presents opportunities and risks.
Once a company adopts AI, it may expand usage across additional departments and business processes.
However, improvements in the performance or pricing of competing models could influence purchasing decisions.
Anthropic emphasized that future performance will depend not only on acquiring additional customers but also on increasing usage among existing customers.
4. Why Did Anthropic Return to an Operating Loss Despite Soaring Revenue?
One of the most interesting developments in the registration statement concerns operating profitability.
Anthropic recorded approximately $974 million in operating income during the second quarter of 2026.
But in the third quarter, it reported an operating loss of approximately $567 million.
Revenue increased sharply while operating performance deteriorated.
Anthropic identified additional short-term computing expenses as a major reason.
The company said it incurred approximately $5 billion in expenses associated with short-term computing arrangements during the third quarter alone.
Short-term computing capacity can be more expensive than resources secured through long-term contracts.
When demand for AI services increases faster than expected, previously contracted infrastructure may be insufficient.
A company must then obtain additional computing capacity through shorter-term arrangements.
The challenge is pricing.
Resources purchased at short notice may cost more than capacity secured in advance under long-term agreements.
Anthropic said these additional expenses significantly affected its operating margin during the quarter.
Approximately $2 billion in noncash expenses associated with a donation-matching program also contributed to the result.
However, the company's adjusted operating income followed a different pattern.
Anthropic reported adjusted operating income of approximately $2.2 billion in the second quarter and $2.5 billion in the third.
Its adjusted operating margin nevertheless declined from 19% to 15%.
The figures show that Anthropic's business is expanding rapidly, but securing enough computing resources to meet demand remains costly.
5. How Should Investors Interpret a $23.3 Billion Net Loss?
Anthropic's third-quarter net loss of $23.291 billion is a striking figure.
But it would be inaccurate to interpret the loss as meaning that the company spent an equivalent amount of cash on operations during the quarter.
A significant portion resulted from accounting adjustments related to changes in the fair value of convertible notes and derivative liabilities.
The associated losses totaled approximately $21.936 billion.
A major factor was the increase in the assessed value of certain convertible financial instruments as Anthropic's enterprise valuation rose.
Those accounting losses did not mean that the company paid the same amount of cash to outside parties during the quarter.
This distinction is particularly important when analyzing the financial statements of rapidly growing AI companies.
When a company's valuation rises sharply, changes in the fair value of certain convertible financing instruments can create substantial reported accounting losses.
The performance of the underlying business must therefore be examined using separate indicators.
Anthropic reported adjusted net income of approximately $3.167 billion for the third quarter.
However, that figure is a non-GAAP measure defined by the company, not net income calculated under U.S. generally accepted accounting principles.
Consequently, the $23.3 billion GAAP net loss should not be treated entirely as cash outflow.
But adjusted net income should not automatically be interpreted as cash profit either.
The important observation is that extraordinary accounting losses, rapid AI business growth, and increasing infrastructure costs were all present in the same quarter.
6. What Do $895.4 Billion in Computing Commitments Actually Mean?
The most attention-grabbing figure in Anthropic's SEC filing may be approximately $895.4 billion.
That represents aggregate spending commitments under purchase, lease, and related arrangements entered into as of September 30, 2026, and subsequently.
Of that amount, approximately $447.5 billion is expected to be spent by the end of 2030.
Approximately $69.8 billion is associated with obligations due within twelve months after the end of September 2026.
A substantial portion of the remaining commitments is expected to be fulfilled between 2031 and 2045.
These amounts should not be confused with debt that must be repaid immediately or losses that have already been incurred.
The commitments include future computing resources, data center-related services, and lease arrangements.
The timing of expense recognition and cash payments may differ depending on contract terms and when services or resources become available.
Nevertheless, the overall scale is enormous.
Anthropic is moving toward a business structure in which it must manage extensive long-term infrastructure expenditures to develop AI models and serve its customers.
This differs from the financial structure of many conventional software startups.
A software company may expand by developing products while purchasing cloud services from external providers.
Developers of frontier AI models require far more computing capacity.
Securing semiconductors and data center resources for model training and inference is becoming a core competitive capability.
Anthropic's $895.4 billion in commitments illustrates the extent to which physical infrastructure and access to capital are now central to AI competition.
7. Why Does Anthropic Want More Direct Control Over Data Centers?
Anthropic has historically used computing resources obtained through long-term agreements with cloud service providers.
But as demand for AI grows rapidly, its infrastructure procurement strategy is changing.
The company refers to its newer approach as "Anthropic Direct."
Rather than relying exclusively on conventional cloud service arrangements, Anthropic is increasingly procuring AI accelerators directly and using dedicated data center facilities configured for its requirements.
The company said its first dedicated data center began operating in 2026.
This does not mean Anthropic owns every data center it uses.
The contractual arrangements governing facilities, semiconductors, and operations can take different forms.
The significant change is Anthropic's more direct involvement in securing computing infrastructure.
There are economic reasons for this strategy.
By designing and procuring computing resources for long-term use, the company may be able to reduce the costs associated with sudden increases in demand.
It can also plan data center capacity separately from purchases of AI accelerators.
Constructing data centers requires considerable time.
The specific types and quantities of AI chips needed, however, may change as technology develops.
Securing facility capacity first and deciding on the exact semiconductor configuration later could provide flexibility.
Anthropic expects this approach to help manage long-term computing costs.
But it introduces additional risks.
If infrastructure secured through long-term commitments is not sufficiently utilized, the associated costs could become a substantial burden.
Anthropic must demonstrate that it can accurately forecast demand, secure appropriate computing capacity, and use those resources efficiently.
8. Why Has AI Become an Industry Requiring Enormous Upfront Investment?
Training advanced AI models requires substantial computing resources.
But the cost of operating an AI business does not end when training is complete.
Each time a user submits a question, the model must perform inference.
Complex coding tasks, sophisticated analysis, and long-running AI agents may require additional computation.
Research computing is also necessary to improve existing models and develop new ones.
Anthropic said it manages computing capacity for these activities as a flexible pool of resources.
The challenge is that infrastructure procurement and revenue generation occur on different timelines.
Computing resources are frequently secured under long-term agreements twelve to eighteen months before they are needed.
A company must therefore commit to significant future capacity based on forecasts of customer demand.
Once contracted infrastructure becomes operational, associated expenses begin.
But it may take time for that capacity to generate sufficient revenue.
This mismatch can cause substantial fluctuations in operating margins.
During a quarter when new computing capacity becomes available, expenses may increase before customer usage catches up.
Profitability may improve later as utilization grows.
Anthropic's return to an operating loss in the third quarter illustrates this pattern.
For AI companies, improving model performance alone is therefore insufficient.
Forecasting future demand and procuring computing resources have become critical business capabilities.
9. Why Isn't a Large Cash Reserve Enough?
At the end of September 2026, Anthropic reported approximately $131.8 billion in cash and short-term investments.
Including available credit facilities and other sources, total liquidity amounted to approximately $146.6 billion.
That is a substantial financial position.
Anthropic also said its strategic partnerships provide additional financing capabilities.
However, the company's approximately $895.4 billion in future spending commitments raise another question.
Can existing financial resources cover all those obligations?
Anthropic said it intends to meet its investment requirements through future revenue growth and additional capital financing.
The IPO is also intended to expand its financing options and financial flexibility.
This structure suggests that continued business growth and access to capital markets may remain important to Anthropic's future.
If AI market growth slows or infrastructure development costs increase, financing requirements could become more difficult to manage.
Certain data center projects may also depend on the financing capacity of external investors and financial institutions.
Anthropic identified these risks in its registration statement.
Its substantial cash holdings therefore do not eliminate the risks associated with its long-term infrastructure investment program.
10. From AI Model Developer to Integrated AI Platform Company
Anthropic is best known as the developer of Claude.
But its business extends beyond the model itself.
The company provides a platform that allows developers to integrate AI into their own applications.
It also operates Claude applications that enterprises and individual customers can use directly.
Its model portfolio allows customers to select systems according to performance requirements and costs.
Within this structure, Anthropic's objective is not simply to attract customers through the technical superiority of one model.
It wants enterprises to use AI continuously and rely on Claude across multiple business functions.
According to the filing, more than half of customers generating at least $100,000 in trailing-twelve-month revenue used both the Claude platform and at least one Anthropic first-party application during the third quarter of 2026.
This indicates that Anthropic is pursuing a strategy connecting models, platforms, and enterprise applications.
Rather than limiting customers to API calls, the company is encouraging them to complete more work within the Claude ecosystem.
If successful, this could increase revenue per customer.
However, an environment in which enterprises can freely switch among competing AI models will continue to create pressure on prices and performance.
Anthropic must therefore demonstrate not only technological strength but also measurable economic value in customers' actual operations.
11. Where Is Anthropic Competing with OpenAI and Google?
Competition in artificial intelligence is often presented as a comparison of model capabilities.
But enterprise customers consider a broader range of factors when adopting AI.
Reasoning and coding performance matter.
So do pricing, response speed, reliability, security, data integration, and service availability.
Anthropic views enterprise AI, coding, and agent-based workflows as particularly important markets.
At the same time, it reaches customers through major cloud environments including AWS, Google Cloud, and Microsoft Azure.
This distribution strategy provides access to a broad range of enterprise customers.
But relationships with cloud providers are complicated.
These companies are important partners to Anthropic.
They may also compete with Anthropic by providing their own AI models and services.
Furthermore, they influence access to the semiconductors and data centers necessary to operate AI systems.
Anthropic's competitive position therefore depends not only on model performance but also on the relationships it maintains with cloud and infrastructure partners.
Anthropic Direct can be understood partly as an effort to adjust its dependence on external cloud providers.
However, greater control over infrastructure does not eliminate supply-chain risks.
It creates additional responsibilities involving semiconductor procurement, data center operations, electricity, and financing.
12. Anthropic's Founders Will Retain 50.1% of Voting Power After the IPO
Anthropic's governance structure is as important as its financial disclosures.
The company has designed a voting arrangement that differs from the structures used by many conventional publicly traded corporations.
After the IPO, Class A shares held by public investors are expected to carry one vote per share.
However, a separate entity associated with Anthropic's founders, Founder LLC, is expected to receive one Class F share.
That special share is designed to represent 50.1% of the total voting power on ordinary shareholder voting matters.
This arrangement allows the founders to retain significant influence over important corporate decisions.
Another distinctive component is the Long-Term Benefit Trust, or LTBT.
Through Class T shares, the trust has authority to appoint or remove a majority of the company's directors.
The governance system therefore combines founder control over ordinary shareholder votes with the public-benefit trust's influence over board composition.
Anthropic argues that this structure is necessary to preserve its long-term commitment to AI safety and public benefit.
For ordinary investors, however, the arrangement presents important considerations.
Purchasing shares may not provide a corresponding degree of influence over corporate management.
Conflicts could also arise if public shareholders, founders, and the trust disagree about business priorities or safety policies.
The IPO is therefore more than the public listing of an AI company.
It is also a test of how public-benefit objectives, founder control, and outside shareholder rights can coexist.
13. Why Has Anthropic Incorporated Public Benefit into Its Governance?
Anthropic is organized as a public benefit corporation, or PBC, under Delaware law.
While conventional corporations focus heavily on shareholders' economic interests, a PBC is designed to consider specified public-benefit objectives and stakeholder interests alongside financial performance.
Anthropic identifies AI safety and responsible development as central corporate purposes.
The registration statement also disclosed financial and equity arrangements intended to support those objectives.
Anthropic said that at the end of June 2026 it contributed Class N shares representing 5% of its fully diluted equity to a public-benefit fund.
It also established a mechanism under which additional equity may be contributed, at the board's discretion, when the company's share price rises by 50% under specified conditions.
The arrangement is intended to help ensure that some of the economic value generated by AI technology supports public-benefit activities rather than flowing exclusively to shareholders.
However, the actual social outcomes produced by these contributions and subsequent fund distributions will need to be evaluated separately.
Certain future contributions also depend on decisions made by the board.
It is therefore important to distinguish declared public-benefit commitments from actual spending and measurable outcomes.
That distinction will become an important criterion for assessing whether Anthropic maintains its AI safety-oriented identity after becoming a public company.
14. What Is the Real Purpose of Anthropic's IPO?
Anthropic said the proposed IPO is intended to increase financial flexibility and establish additional access to capital through the public markets.
The proceeds are expected to support working capital, personnel expenses, research and development, and infrastructure investment.
That includes computing infrastructure for AI.
Anthropic must continue securing enormous computing resources.
At the same time, it needs to expand its enterprise customer base and develop new models.
In a business with these characteristics, reliable access to financing becomes an important competitive advantage.
The IPO should therefore not be viewed solely as an opportunity for existing investors to convert their shares into cash.
It also represents a capital-raising strategy intended to sustain competition in advanced AI.
However, the amended registration statement did not establish the final offering price or the number of shares to be offered.
As a result, the amount of capital Anthropic will ultimately raise and its valuation at the time of listing remain undetermined.
The timetable and investor demand may also change with market conditions.
At this stage, the confirmed development is that Anthropic has submitted an amended registration statement to the SEC and is pursuing an initial public offering.
15. Does the Future of AI Depend More on Computing Infrastructure Than Models?
Perhaps the most important development revealed by Anthropic's filing concerns the structure of AI businesses.
In 2023, Anthropic generated $41 million in revenue.
By the third quarter of 2026, quarterly revenue alone had reached approximately $17 billion.
The growth is extraordinary.
But supporting that expansion requires vast amounts of computation.
Developing high-performance AI models demands research computing.
As more enterprise customers use AI, inference infrastructure must expand.
Long-running AI agents and complex coding workflows may increase demand for computation even further.
AI companies must therefore forecast future requirements for data centers and semiconductors while continuing to develop their models.
They enter into large contracts and establish financing plans to secure that capacity.
Anthropic's approximately $895.4 billion in future spending commitments illustrate this industrial transformation.
AI companies are becoming software developers and large-scale computing infrastructure procurers and operators at the same time.
However, the size of a long-term infrastructure commitment does not automatically translate into competitive strength.
If customer demand falls below expectations, contracted computing resources may remain underutilized.
If demand grows much faster than expected, companies may have to purchase expensive short-term capacity.
Ultimately, the economics of AI will depend on how effectively companies balance model intelligence, customer demand, computing efficiency, and financing capabilities.
The Financial Bill for AI's Explosive Growth Has Arrived
Anthropic's IPO filing illustrates a new phase in the development of the artificial intelligence industry.
AI companies can no longer be evaluated solely on technological capability and future growth potential.
They must disclose actual revenue, customer numbers, operating costs, cash flow, infrastructure commitments, and governance structures for assessment by public markets.
Anthropic generated approximately $33.2 billion in revenue during the first nine months of 2026.
Its enterprise customer base is expanding rapidly.
Third-quarter revenue reached approximately $17 billion.
Yet operating results returned to a loss during the same quarter, while the company recorded a GAAP net loss of approximately $23.3 billion.
Long-term computing and lease-related spending commitments totaled approximately $895.4 billion.
These figures are not contradictory.
They demonstrate that an AI company can grow at extraordinary speed while requiring enormous amounts of capital to sustain that growth.
Anthropic's principal strength is the rapid expansion of enterprise demand for Claude.
Its central risk is the escalating cost of the computing resources required to serve that demand and develop future models.
Evaluating Anthropic's value will increasingly require examining the economics of its computing infrastructure alongside model performance.
How much computing expense is necessary to generate each dollar of revenue?
How efficiently can the company use infrastructure secured through long-term contracts?
How much additional capital will it need to raise?
Investors will also need to assess how Anthropic's unusual governance arrangements, including founder voting control and the public-benefit trust, influence the company after its public listing.
Anthropic's IPO is not simply an event intended to demonstrate the success of its AI technology. It is also a test of whether the enormous demand created by artificial intelligence can support a sustainable business capable of financing hundreds of billions of dollars in infrastructure commitments.
Expectations for the future of AI remain high.
But building that future requires extraordinary amounts of money.
Anthropic's SEC filing puts a concrete financial scale on that challenge.
The market must now decide not only how intelligent Claude is, but also how sustainable the business supplying that intelligence can become.