Automakers generally need to sell more vehicles to grow.
As sales volumes increase, revenue rises, factories operate at higher utilization rates, and manufacturers gain opportunities to reduce production costs.
That is why vehicle sales and market share are among the automotive industry's most important performance indicators.
But one company is operating according to a different formula.
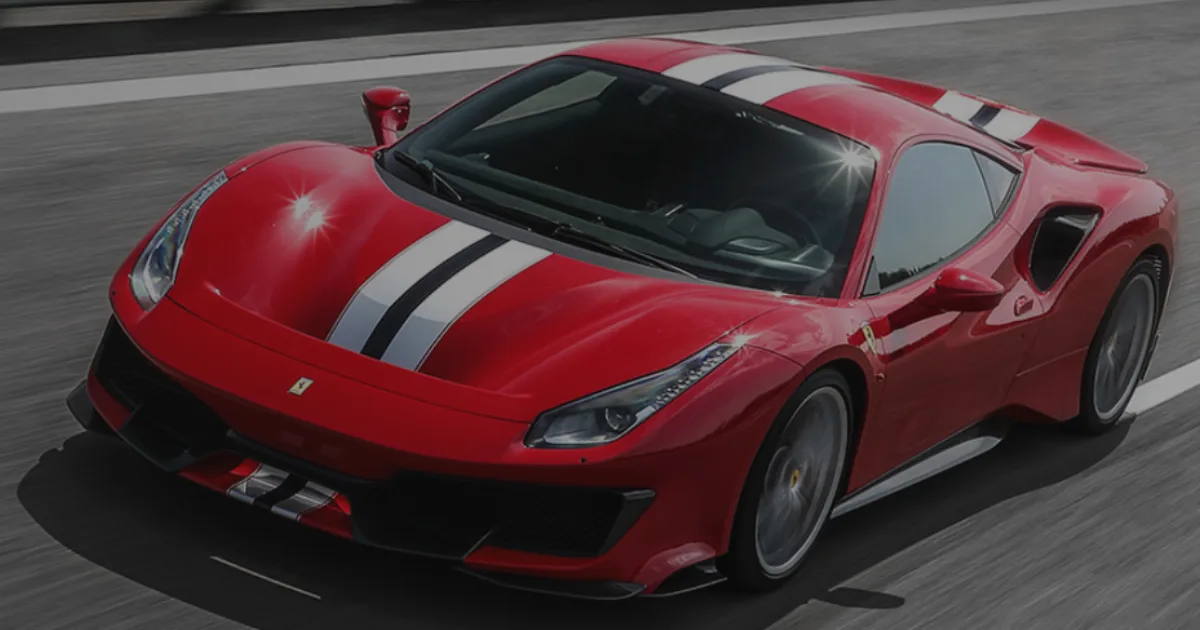
Ferrari, the Italian luxury sports car manufacturer.
In its third-quarter results announced on November 3, 2026, Ferrari reported higher revenue and operating profit despite delivering fewer vehicles.
The company delivered 3,368 cars during the quarter, down 33 from 3,401 a year earlier.
That represents a decline of approximately 1%.
Revenue, however, increased 7%, from €1.766 billion to €1.896 billion.
Operating profit rose 12%, from €503 million to €563 million.
The operating margin improved from 28.4% to 29.7%.
Ferrari sold fewer cars but generated more revenue and profit.
An even more interesting figure concerns cash flow.
Industrial free cash flow reached €567 million in the third quarter, increasing 43% year over year.
The results suggest that product mix and customers' personalized specifications had a greater influence on financial performance than vehicle volume alone.
Ferrari identified increased deliveries of its F80 supercar and stronger personalization demand, particularly around the 296 Speciale family, as major contributors to growth.
The company also reported that its order book extends into 2028.
Together, these figures reveal a fundamental aspect of Ferrari's business strategy.
Ferrari is focusing less on how many cars it can sell and more on how much value customers are willing to place on each individual vehicle.
How Did Ferrari Generate Nearly €1.9 Billion in Revenue from 3,368 Deliveries?
Ferrari generated €1.896 billion in revenue during the third quarter of 2026.
Of that amount, €1.586 billion came from its cars and spare parts business, representing approximately 84% of total revenue.
Another €220 million came from sponsorship, commercial activities, and brand-related operations.
Other revenue accounted for €90 million.
Revenue from cars and spare parts increased approximately 7% compared with the same period a year earlier.
Vehicle deliveries, meanwhile, declined.
The difference can largely be understood through changes in product mix and customer personalization.
Dividing cars and spare parts revenue of €1.586 billion by 3,368 deliveries produces approximately €471,000 per vehicle.
Applying the same calculation to the previous year's figures produces approximately €435,000.
That represents an increase of roughly 8%.
However, this figure should not be described as Ferrari's actual average vehicle selling price.
Revenue from cars and spare parts includes more than vehicle sales. It also reflects spare parts, personalization-related revenue, and other components.
Furthermore, the timing and scope of revenue recognition may not correspond perfectly with vehicle deliveries.
The calculation is therefore a reference indicator comparing segment revenue with deliveries, not Ferrari's officially reported average selling price.
Nevertheless, the underlying trend is significant.
Revenue from the business increased even as deliveries declined.
That is consistent with Ferrari's explanation that stronger product mix and additional customer-selected specifications supported growth without an increase in vehicle volumes.
Why Did Ferrari's Growth Begin with the F80?
One of the principal contributors to Ferrari's stronger operating performance was the F80.
The F80 is a limited-production Ferrari supercar.
Its launch price has been reported at approximately €3.6 million.
That places it far above Ferrari's regular production sports cars.
In its official financial disclosures, Ferrari said F80 deliveries were progressing according to plan and that a stronger contribution from high-value models had supported profitability.
The significance of a vehicle such as the F80 lies in its revenue contribution relative to delivery volume.
When deliveries of exceptionally expensive limited-production models increase, revenue can rise substantially without a corresponding increase in total vehicles delivered.
Products combining advanced technology, distinctive design, and scarcity can command premium prices.
For customers, such automobiles may represent something beyond transportation.
The ownership experience, the history of the Ferrari brand, exclusivity, and potential collectible value may all influence purchasing decisions.
However, Ferrari has not disclosed the F80's individual operating profit per vehicle or the exact number delivered during the quarter.
It is therefore not possible to calculate precisely how much operating profit the F80 contributed independently.
What can be established is that Ferrari identified the F80 as an important factor in improving its product mix.
No Two Ferraris Need to Be Exactly Alike
Another important engine of Ferrari's growth is personalization.
Customers can select exterior colors, materials, interior finishes, and design details according to their individual preferences.
Conventional automobile buyers can also choose among different trims and optional equipment.
But in the luxury automobile market, personalization becomes more than a collection of convenience features.
It can become an important component of the product's value.
Customers do not simply select a finished vehicle.
They may also value the experience of configuring a car that reflects their own identity and preferences.
Even vehicles belonging to the same model family can differ substantially in exterior colors, interior materials, special finishes, and individual design details.
Ferrari said personalization contributions were stronger than expected during the quarter.
The 296 Speciale family played a particularly important role in this trend.
During the earnings conference call, management also indicated that personalization-related revenue exceeded 21% of cars and spare parts revenue.
That was above the company's initial annual target of approximately 20%.
The figure suggests that personalization has become a major revenue component rather than merely an additional source of optional equipment sales.
However, the proportion of revenue attributable to personalization does not establish the operating margin generated by those activities.
Detailed information about the costs of individual specifications, incremental production expenses, and pricing arrangements has not been disclosed.
Nevertheless, personalization is clearly an important component of Ferrari's competitive positioning.
Why Does Personalization Change the Economics of Automobile Manufacturing?
Standardization is a major competitive advantage in mass-production industries.
Producing large quantities of identical products allows companies to simplify manufacturing processes and reduce unit costs.
Automakers frequently use shared platforms and components to achieve economies of scale.
Ferrari pursues a different form of value creation.
While maintaining core vehicle performance and brand identity, it uses customer-selected specifications to offer differentiated products.
The value perceived by customers does not necessarily increase in direct proportion to manufacturing costs.
A buyer selecting a special paint color or interior material may be paying not only for the physical materials involved but also for rarity, individuality, and the experience of creating a personally meaningful product.
This is where conventional automotive options and luxury-brand personalization strategies intersect.
Ferrari is using this approach to increase the contribution of high-value products to revenue.
Personalization, however, can also make manufacturing and supply-chain operations more complex.
As customer orders become more varied, managing components, materials, and production schedules becomes more difficult.
A successful personalization strategy therefore requires companies to offer desirable choices while maintaining consistent product quality and delivery schedules.
Ferrari's competitive advantage may lie not simply in charging high prices for optional specifications, but also in its ability to manufacture highly individualized vehicles efficiently.
Ferrari's Order Book Extends into 2028
Ferrari reported that its order book extends into 2028.
This means customers placing new orders may face considerable waiting periods before delivery.
However, it does not mean every Ferrari model has an identical waiting list extending into 2028.
Order timing and delivery schedules can vary by model, market, and specification.
Nevertheless, a long order book provides an indication of the company's demand base.
Conventional automakers generally seek to expand production capacity and serve as many customers as possible.
In the luxury automobile market, however, increasing supply without restraint is not necessarily advantageous.
If a product becomes too widely available, the scarcity supporting its brand value may weaken.
Ferrari has long maintained a strategy of managing production volumes over time to preserve exclusivity while balancing demand.
Its latest results are consistent with that approach.
However, a long order book does not guarantee that every order will ultimately become a completed sale.
Customers' financial circumstances, economic conditions, and vehicle launch schedules can affect future deliveries.
That is why an order book should not be treated as equivalent to recognized revenue.
Deliveries Fell Sharply in Greater China
Ferrari's strong financial results do not mean every regional market performed equally well.
Vehicle deliveries varied considerably by geography.
In Europe, the Middle East, and Africa, or EMEA, third-quarter deliveries reached 1,487 vehicles, an increase of 38 year over year.
Deliveries in the Americas rose by five vehicles to 1,050.
The Asia-Pacific region excluding mainland China, Hong Kong, and Taiwan recorded 688 deliveries, an increase of 29.
Greater China, however, experienced a substantial decline.
Deliveries across mainland China, Hong Kong, and Taiwan fell from 248 to 143 vehicles.
That represents a reduction of 105 vehicles, or approximately 42%.
Considering that Ferrari's total global deliveries declined by only 33 vehicles, the regional difference is particularly striking.
Increases elsewhere offset a substantial portion of the decline in Greater China.
However, these figures alone do not establish that underlying consumer demand in the region declined by 42%.
Ferrari's delivery volumes can also be influenced by production schedules, model transitions, and regional vehicle allocations.
The earnings materials did not provide a detailed breakdown of the causes behind the decline in Greater China.
It would therefore be premature to attribute the reduction specifically to weaker Chinese purchasing power or a particular regulatory development.
What the figures do show is the importance of regional differences in demand and supply management within the luxury automobile industry.
Ferrari's ability to increase revenue and profit despite lower deliveries also demonstrates why financial performance cannot be assessed solely through regional vehicle volumes.
Ferrari Grew While Transitioning Between Major Models
Ferrari described 2026 as a period of important model transitions and changes in its product portfolio.
During the quarter, deliveries increased for the Amalfi, 296 Speciale, 12Cilindri Spider, and Purosangue.
The 849 Testarossa and 296 Speciale Aperta were progressing through production and delivery ramp-up phases.
Customer deliveries of the 849 Testarossa Spider also began.
Meanwhile, the Roma Spider, 296 GTS, and SF90 XX family were approaching the end of their production and sales cycles.
Model transitions are an important process in automobile manufacturing.
As production of older models declines, new models require time to reach stable manufacturing volumes.
This can temporarily reduce production and deliveries.
The early stages of manufacturing a new model may also require additional quality verification, production-line adjustments, and component supply management.
Ferrari was managing several such transitions simultaneously during the quarter.
Nevertheless, improvements in product mix and personalization supported revenue and profit growth.
From this perspective, the results illustrate a strategy of increasing profitability through portfolio evolution rather than relying solely on higher sales volumes.
What Does a 29.7% Operating Margin Mean?
Ferrari generated €563 million in operating income during the third quarter.
Its operating margin reached 29.7%.
That represented an increase of 1.3 percentage points from the same period a year earlier.
EBITDA rose to €753 million, with an EBITDA margin of 39.7%.
This indicates substantial earnings before interest, taxes, depreciation, and amortization.
Ferrari identified a stronger mix of high-value vehicles and increased personalization as major contributors to improved profitability.
At the same time, higher depreciation associated with new model production and increased marketing expenses placed pressure on margins.
In other words, profit did not rise because every category of expenditure declined.
Operating income increased despite additional costs associated with new products because the revenue mix improved.
This illustrates the extent to which Ferrari's business model differs from one based purely on expanding sales volumes.
However, a 29.7% operating margin should not be treated as a general benchmark achievable by every premium automobile manufacturer.
Ferrari operates within a distinctive commercial structure built around scarcity, brand equity, and long-term customer relationships.
Why Did Free Cash Flow Increase 43%?
Ferrari's financial performance improved not only in accounting profits but also in cash generation.
Industrial free cash flow reached €567 million during the third quarter.
That was 43% higher than the €396 million reported a year earlier.
Ferrari attributed the improvement to stronger earnings and favorable working-capital developments.
Capital expenditures, meanwhile, represented a source of cash outflow.
The financial statements reported third-quarter operating cash flow of €737 million.
Investments in property, plant, equipment, and intangible assets amounted to €226 million.
Subtracting those expenditures produces consolidated free cash flow of approximately €511 million.
Yet reported industrial free cash flow was higher, at €567 million.
The difference arises because the industrial free cash flow measure excludes the cash flow effects of financial services activities.
Ferrari also operates financing services associated with its vehicles.
Industrial free cash flow is designed to provide a view of cash generation from the company's industrial operations without incorporating the effects of those financing activities.
The €567 million industrial free cash flow figure should therefore be distinguished from consolidated free cash flow of €511 million.
This distinction is also important when comparing Ferrari's cash-generation capacity with that of other automakers.
Ferrari Moves to a €219 Million Net Industrial Cash Position
Ferrari's financial structure also improved during the quarter.
At the end of June 2026, the company reported net industrial debt of €131 million.
By the end of September, it had moved to a net industrial cash position of €219 million.
This means that cash and related financial resources attributable to industrial operations exceeded the corresponding net debt position.
The figure is calculated by distinguishing Ferrari's industrial activities from its financial services operations.
It does not mean that the company's total outstanding borrowings disappeared.
In fact, total borrowings stood at approximately €3.122 billion at the end of September.
Nevertheless, after separating financial services-related assets and liabilities, Ferrari's industrial operations had achieved a positive net cash position.
The company continued returning capital to shareholders.
Ferrari repurchased approximately €173 million of its own shares during the third quarter.
Additional repurchases followed in October.
The company is pursuing a multiyear share buyback program of approximately €3.5 billion through 2030.
Ferrari is therefore combining stronger cash generation with continued shareholder distributions.
Why Did Ferrari Raise Its 2026 Financial Guidance?
Ferrari revised several elements of its full-year 2026 financial outlook upward.
Its revenue forecast increased from approximately €7.6 billion to around €7.65 billion.
The adjusted EBITDA target rose from at least €2.97 billion to at least €3.0 billion.
The adjusted operating income target increased from at least €2.26 billion to at least €2.285 billion.
Guidance for adjusted diluted earnings per share increased from at least €9.68 to at least €9.85.
The company also revised its industrial free cash flow outlook from a previous target of at least €1.55 billion to a figure of up to €1.65 billion.
The wording of the last item requires particular care.
The previous figure represented a minimum target, while the revised guidance used an upper-limit formulation.
It should therefore not be interpreted in exactly the same way as the increases in the minimum targets for other financial indicators.
Ferrari identified three principal reasons for the guidance changes.
Personalization demand was stronger than anticipated.
Foreign-exchange headwinds were lower than originally expected.
And the company revised assumptions related to its position in the Formula One championship.
Model transitions and greater deliveries of high-value vehicles were also expected to support full-year results.
However, financial guidance represents management's expectations for future performance.
Actual results will depend on delivery schedules, foreign-exchange movements, production conditions, and market developments through the end of the year.
Ferrari's Business Extends Beyond Automobiles
Another noteworthy aspect of Ferrari's earnings presentation is that the company does not define itself solely as an automobile manufacturer.
It organizes its activities around three principal areas.
Racing.
Sports Cars.
Lifestyle.
The sports car business involves designing and manufacturing automobiles.
Racing includes participation in motorsport competitions such as Formula One and the World Endurance Championship.
Lifestyle encompasses apparel, collectibles, and customer experiences associated with Ferrari's brand identity.
These businesses are not completely separate.
Motorsport reinforces Ferrari's technological performance credentials and brand identity.
Sports cars translate those attributes into physical products.
Lifestyle activities allow the brand experience to reach people who may not own a Ferrari.
This structure illustrates Ferrari's strategy of creating economic value from its brand beyond vehicle sales.
During the quarter, sponsorship, commercial activities, and brand-related revenue reached €220 million, increasing 4% year over year.
Racing sponsorship and lifestyle initiatives contributed to growth.
Lower commercial revenue associated with the previous year's Formula One championship ranking partially offset those gains.
This demonstrates that racing results influence not only Ferrari's public image but also aspects of its financial performance.
Does Ferrari Sell Cars or the Experience of Owning One?
This question is central to understanding Ferrari's business strategy.
Customers may not purchase a Ferrari simply because they want to travel quickly.
Performance, design, and driving experience are important.
But brand history, scarcity, and participation in a community of owners and enthusiasts can also influence purchasing decisions.
Ferrari actively cultivates these elements.
During the quarter, the company expanded experiences for customers and fans through activities including Casa Ferrari and Fan Zone.
It also introduced a capsule collection and collectible projects associated with the Monza Grand Prix.
Even when such activities do not directly produce vehicle sales, they can strengthen relationships between the brand and its customers.
In luxury industries, the experience following a purchase can be as important as the original transaction.
Customers who maintain a strong emotional connection to a brand may be more inclined to purchase future models or engage with related products and services.
However, Ferrari's financial disclosures did not quantify how much these customer experience programs increased repeat vehicle purchases.
It would therefore be inaccurate to attribute a specific portion of revenue growth directly to those activities.
What can be established is that Ferrari treats customer relationships and lifestyle experiences as important business priorities.
Will Ferrari's First Electric Car, Luce, Change Its Strategy?
Ferrari is seeking to introduce new technologies while preserving its established brand strategy in the era of electrification.
During the quarter, the company highlighted a record-setting auction result for the "Chassis 0" associated with its Luce electric vehicle project at Monterey Car Week.
Luce has attracted attention as Ferrari's first fully electric vehicle project.
According to Reuters reporting following the earnings announcement, Ferrari's 2027 Luce allocation had already been assigned to customers.
This can be interpreted as an early indication of customer demand for Ferrari's electric vehicle.
However, it does not establish future production volumes, actual deliveries, or profitability.
Electric cars present engineering challenges that differ from those of conventional internal-combustion supercars.
Battery weight, thermal management, driving range, charging experience, sound, and driving characteristics all matter.
Ferrari customers may place particular value on the emotional experience of driving, not merely on transportation performance.
For that reason, the success of electrification may depend on more than acceleration figures or electric motor output.
A central question is how Ferrari can reproduce its distinctive emotional appeal through new technology.
Luce could become an important test of whether Ferrari can preserve its strategy of exclusivity and customer-centered value creation in the electric vehicle era.
Tesla and Ferrari Reveal Two Different Futures for the Automobile
The automobile industry is witnessing contrasting strategic developments in 2026.
Tesla is expanding beyond vehicle sales toward autonomous driving, robotaxis, and AI-powered mobility services.
Ferrari, meanwhile, is reinforcing the exclusivity and personalization associated with cars that customers own and drive themselves.
Both companies consider technology essential.
But their growth strategies are moving in different directions.
Tesla's robotaxi strategy focuses on how much transportation service an individual vehicle can provide.
Vehicle utilization, service demand, and autonomous-driving software performance become central factors.
Ferrari focuses on how much value a customer places on a particular automobile.
Product mix, personalization, scarcity, and customer relationships become major competitive elements.
One model is centered on the economics of making vehicles operate more frequently.
The other is centered on the economics of making individual vehicles more desirable and distinctive.
Of course, Tesla and Ferrari should not be viewed as representing mutually exclusive strategies.
Tesla also sells expensive vehicles, while Ferrari continues investing in technological innovation and electrification.
Nevertheless, their recently announced strategies and financial results suggest that the automotive industry's future may develop along more than one path.
Challenges Remain in China and Electrification
Ferrari's results demonstrate that its business model can generate substantial profitability.
But the company still faces important long-term challenges.
The first involves changes in regional markets.
Deliveries in mainland China, Hong Kong, and Taiwan declined significantly year over year.
Ferrari offset much of that reduction through increased deliveries elsewhere and a stronger product mix.
However, the longer-term direction of regional demand will require continued observation.
The second challenge concerns model transitions and development costs.
Ferrari must continue introducing new vehicles and developing technology.
Third-quarter research and development expenses recognized in the income statement increased from €222 million a year earlier to €251 million.
Total research and development activity, including capitalized development expenditure, increased to €269 million.
These investments support future competitiveness but can also create pressure on profitability.
The third challenge is balancing electrification with brand identity.
Ferrari must introduce new technologies while preserving the exclusivity and driving experience expected by its existing customers.
The issue is not simply whether Ferrari can manufacture an electric vehicle.
It is whether an electric Ferrari can deliver the distinctive value customers associate with the brand.
The Question Ferrari Raises for the Automobile Industry
Ferrari's third-quarter 2026 results invite a reconsideration of how automotive companies can grow.
Vehicle deliveries declined.
Yet revenue and operating income increased.
Industrial free cash flow improved even faster.
Product mix and personalization contributed to growth, while the order book extended into 2028.
The results demonstrate that growth in the automotive industry does not necessarily require higher sales volumes.
Of course, Ferrari's business model cannot easily be replicated by conventional automakers.
Scarcity, brand history, customer loyalty, and the symbolic value of a product require years of development.
However, the underlying principle may apply to other industries.
Selling more units and enabling customers to experience greater value from each product are different growth strategies.
When customers perceive a product as a distinctive experience rather than simply a collection of functions, and when they can express individual preferences through that product, companies may create value without relying exclusively on volume.
Ferrari's latest financial results provide evidence of that possibility.
Nevertheless, sustaining such performance requires maintaining customer demand, product appeal, manufacturing quality, and brand exclusivity.
Today's high operating margins are not automatically guaranteed in the future.
A Company Where Selling Fewer Cars Is Not Necessarily a Problem
For many automakers, declining sales volumes signal deteriorating business performance.
Ferrari's third quarter of 2026 produced a different outcome.
Deliveries of 3,368 vehicles were lower than a year earlier.
Yet revenue increased to €1.896 billion.
The operating margin improved to 29.7%, while the EBITDA margin reached 39.7%.
High-value models and personalization demand supported profitability.
At the same time, Ferrari continued investing in new vehicles, electrification, customer experiences, and motorsport.
In this business model, the important question is not simply how many cars a manufacturer produces.
What matters may be which cars it offers, to which customers, and at what perceived value.
Ferrari is a brand that can command premium prices while giving customers reasons to wait for its products.
Its objective is to convert that willingness to wait into sustainable revenue and profit.
Such a strategy requires maintaining scarcity while continuously innovating in technology and product development.
Ferrari's competitive advantage is not simply that it produces relatively few cars. It is that customers remain willing to pay more for the opportunity to own them.
That is the distinction revealed by the company's latest results.
Economies of scale remain important throughout the automotive industry.
But Ferrari demonstrates that high profitability and strong cash generation can also emerge from a business model that does not depend primarily on maximizing production volume.
As competition to sell more automobiles intensifies, strategies that increase the value customers attach to each individual vehicle may become increasingly important.
Ferrari is demonstrating that strategy through its financial results.